

Hearing the news that someone you love has Alzheimer's disease can feel like your whole world is collapsing around you. In those first heavy moments, your mind races straight to their health, safety, and daily comfort. You worry about giving the right medicines, keeping doctor appointments, and preparing healthy meals every single day.
Yet, as time moves forward, a quiet and heavy challenge starts to grow behind the scenes. That challenge is the financial reality of long-term medical care. While medical needs always come first, managing money and planning for future expenses is just as important for protecting your family's peace of mind.
Let us walk through why financial planning matters so much, how you can start today, what insurance options exist, and how to manage the real costs of care with confidence and calm.
Key Takeaways for Families
- Start early: Begin financial and legal planning right after diagnosis while your loved one can still participate in decisions.
- Review insurance: Check private health policies and workplace benefits to see what dementia and long-term care costs are covered.
- Talk openly: Have honest family discussions about future expenses, caregiving duties, and shared financial responsibilities.
- Anticipate care costs: Prepare for expenses like specialized medicines, home safety upgrades, professional caregivers, and residential facilities.
- Seek guidance: Work closely with your family doctor and legal advisors to build a strong, supportive safety net.
BMI Calculator
Know your body mass index (BMI) and weight classification
Why Plan Ahead for Alzheimer's Financial Care?
Simply put, Alzheimer's disease is a progressive condition. This means its symptoms get worse slowly over time. The tasks your loved one can easily handle today might become difficult or impossible in a few months or a year.
As the disease advances, a person gradually loses their ability to manage daily tasks, make important decisions, and handle money safely. For example, someone who drives a car safely today may soon need to stop driving for safety reasons. Someone who manages bank accounts independently may forget passwords or fall victim to financial scams.
Planning ahead brings enormous emotional and financial relief to you, your loved one, and the rest of your family. Making calm choices now prevents panic and confusion during future medical emergencies.
How to Start Building a Solid Financial Plan
You do not have to carry this heavy burden all by yourself. Bringing your family together to talk openly is the very best way to begin. Here are three practical steps to guide your start:
1. Talk Openly as a Family: Gather your family members together to discuss future challenges, expected expenses, and how everyone can share the load. This conversation can feel difficult and emotional, but it is completely necessary for protecting your loved one's future.
2. Consult Your Family Doctor: Speak with your primary doctor about the expected progression of the illness. Your doctor can give you a realistic timeline of future medical needs and connect you with professional social workers or financial counselors who specialize in elder care.
3. Prepare Legal Documents Early: While your loved one still has clear cognitive capacity, set up essential legal papers like a Power of Attorney. This legal step ensures that a trusted family member can make financial and medical decisions if your loved one loses that ability later on.
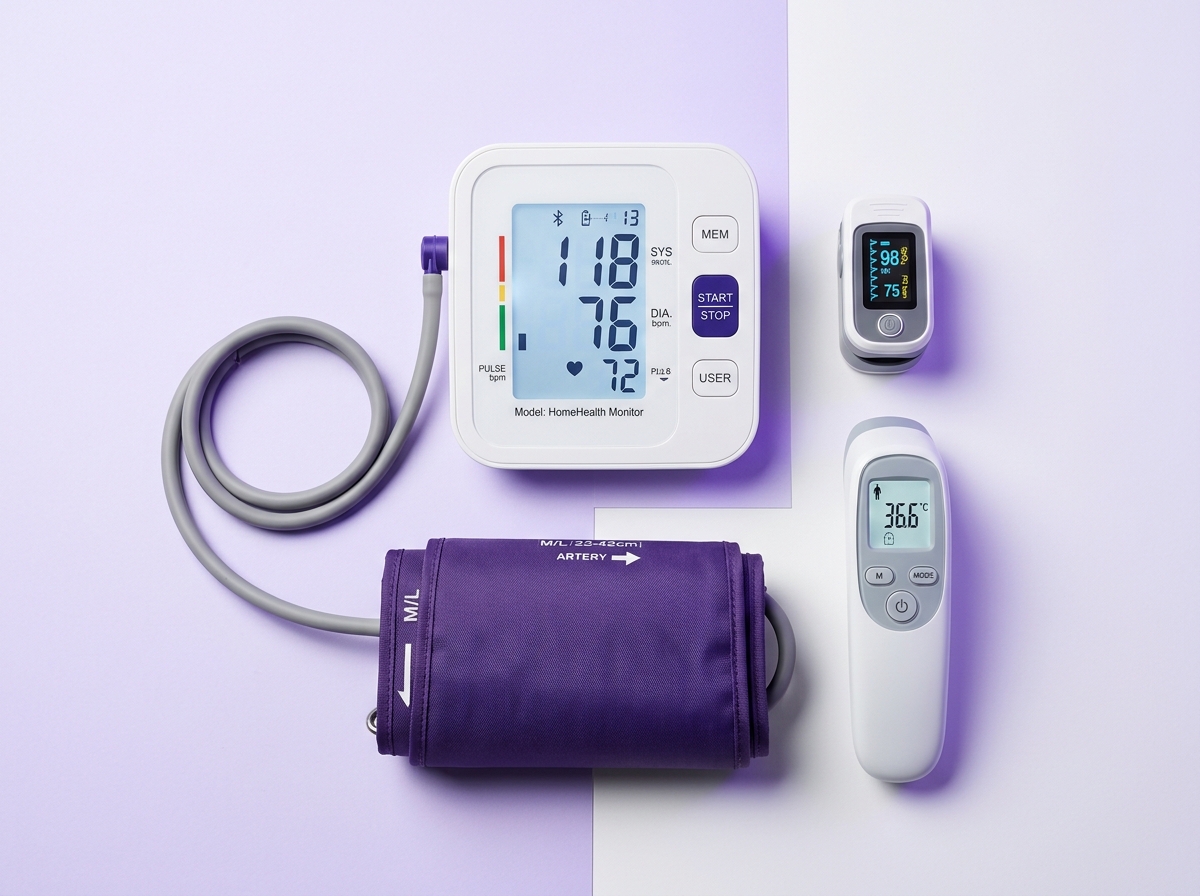
Medical test equipment that can be used at home
Essential home medical devices including blood pressure monitors, oximeters and digital thermometers.
Check Availability →Understanding Financial and Insurance Options
Healthcare systems vary greatly around the world, but every family needs to explore all available financial resources. Knowing what support exists helps you stretch your budget and secure the best possible care.
Do You Have Private Health Insurance?
If you or your loved one holds a private health insurance policy, examine it closely as your very first step. Insurance rules can be tricky, so knowing your policy details prevents unexpected medical bills.
- Read your policy document carefully: Check whether your insurance plan covers long-term illnesses, neurological disorders, and memory loss or dementia care.
- Understand exact coverage limits: Ask your insurance provider how much money they pay toward doctor fees, hospital stays, medicines, and home care services.
- Ask questions when in doubt: Never hesitate to call your insurance company directly to clarify confusing terms or coverage exclusions.
Employer Benefits and Workplace Coverage
If your loved one or an active family member is currently employed, check with the human resources (HR) department to discover hidden workplace benefits.
- Many employers provide supplemental health insurance coverage that extends to immediate family members.
- Find out if disability insurance or paid family leave policies are available if a working family member needs to step away to provide care.
Public Healthcare Systems and Social Support
Public health services offer incredible support through government hospitals, where initial doctor visits, basic lab tests, and many common medicines are provided at little or no cost. This public safety net is a vital foundation for families.
However, the reality is that long-term conditions like Alzheimer's often require out-of-pocket expenses beyond public hospital services. Costs for specialized medicines, advanced diagnostic scans, and professional home caregivers usually fall directly on the family.
Major Expenses Associated with Alzheimer's Care
Being aware of potential expenses ahead of time makes it much easier to build a realistic financial plan. Here is a breakdown of the primary costs families encounter:
| Expense Category | What to Consider & Plan For |
|---|---|
| Medical Fees & Tests | Regular checkups, specialist consultation fees, brain imaging scans (CT or MRI), and routine blood work. |
| Prescription Medicines | Monthly costs for drugs that manage symptoms or slow cognitive decline. Specialized medicines can sometimes be quite costly. |
| Home Care Services | Hiring trained professional caregivers to assist at home involves ongoing hourly or monthly wages. |
| Home Safety Modifications | Installing grab bars in bathrooms, non-slip flooring, stair gates, and secure door locks to prevent wandering. |
| Specialized Equipment | Purchasing or renting wheelchairs, adjustable hospital beds, walking aids, and incontinence supplies. |
| Residential Care Facilities | In advanced stages when home care is no longer possible, specialized memory care units or nursing homes require significant monthly investment. |
Planning for the future and preparing financially gives you and your family a strong foundation of support throughout this challenging journey.
When to Call the Doctor or Seek Emergency Help
While financial planning is vital, your loved one's immediate physical safety always comes first. Contact your doctor right away or call emergency services (911 in the US/Canada, 999 in the UK, or go to your nearest Emergency Department) if you notice any of the following red flags:
- Sudden, severe confusion or rapid worsening of mental state over hours or days.
- Signs of a physical injury from a fall, such as severe head trauma or broken bones.
- Unexplained high fever, sudden inability to swallow, or signs of severe infection.
- Expressions of self-harm or aggressive behavior that puts the patient or caregivers in immediate danger.
💡 Take-Home Message
You do not have to travel this road alone. Working together, supporting one another, and building a solid plan helps you face this challenge with courage and compassion. Here are the core reminders to keep in mind:
- Plan Early: Begin thinking about finances right after diagnosis. Waiting too long makes decisions much harder.
- Understand Your Insurance: Review private health policies to know your exact coverage limits and exclusions.
- Talk as a Family: Discuss money and future care openly and honestly with all family members involved.
- List Your Expenses: Anticipate future costs like medicines, home care, and doctor visits to build a realistic budget.
- Involve Your Doctor: Speak with your family doctor for medical guidance and referrals to expert support services.
Sources & Medical References
- Alzheimer's Association. (2024). Financial and Legal Planning.
- Mayo Clinic. (2023). Alzheimer's disease: Caregiver support and financial management. Mayo Clinic Patient Care Guide.
- National Institute on Aging (NIA). (2023). Managing Alzheimer's Care Costs. NIH Publication.
- National Health Service (NHS). (2024). Dementia care and financial support options. NHS UK Health Guides.
- Centers for Disease Control and Prevention (CDC). (2024). Caregiving for Alzheimer's Disease and Related Dementias. CDC Public Health Reports.


No comments yet. Be the first to share your question or experience below.